
Indianapolis Auto Insurance Quotes and Company Comparisons
If you live in or commute around the Indianapolis area, you already know that driving here requires patience, defensive skills, and a healthy dose of caution. With major interstates like I-65, I-70, and I-465 converging through the city, the volume of local and commercial traffic creates a unique environment for drivers.
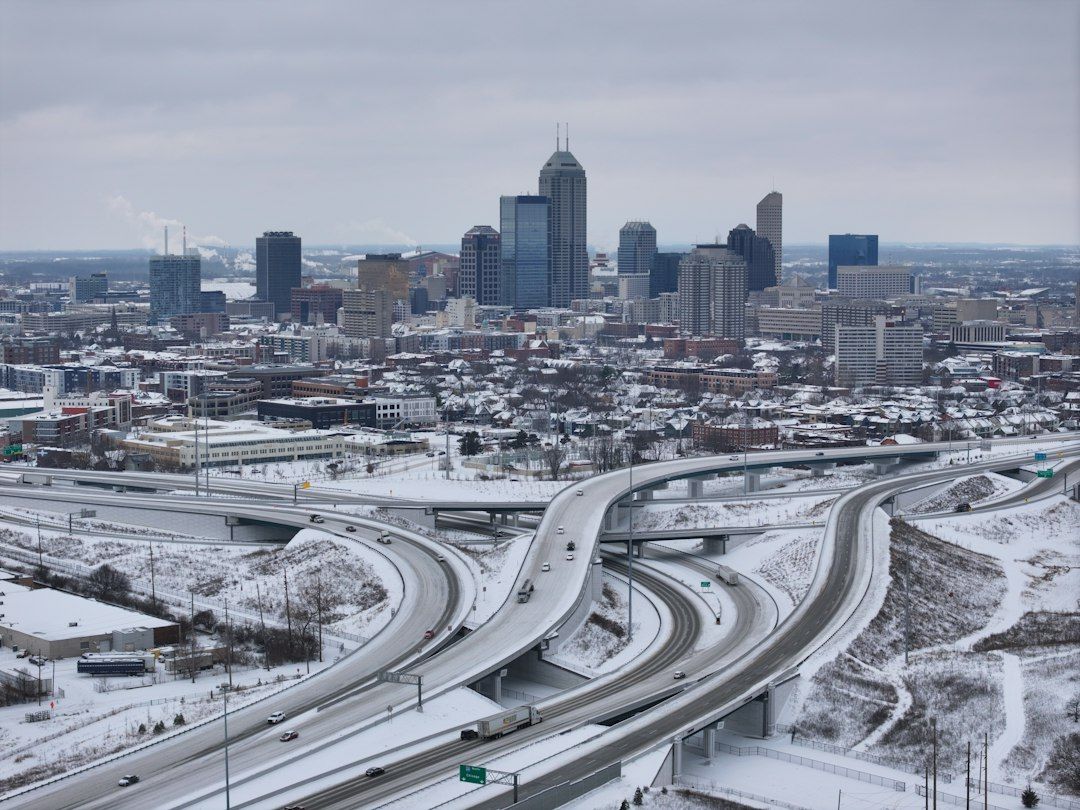
Navigating the Crossroads of America
If you live in or commute around the Indianapolis area, you already know that driving here requires patience, defensive skills, and a healthy dose of caution. With major interstates like I-65, I-70, and I-465 converging through the city, the volume of local traffic mixed with commercial transport creates a unique environment for drivers. Every day, countless Hoosiers share these busy roads, which unfortunately increases the likelihood of fender benders, severe collisions, and property damage.
At The Haley Agency, we spend a lot of time reviewing policies and helping clients understand what they are actually paying for. We notice a recurring theme. Most people just look at the final monthly premium when they compare car insurance quotes in Indianapolis. They assume that if the state says they are legal to drive, they are fully protected.
The reality of modern auto insurance is far more complex. Medical costs are climbing, vehicle repair expenses have skyrocketed due to advanced technology, and distracted driving remains a persistent threat. Comparing auto insurance quotes in Indianapolis requires you to look beyond the top-line number. You need to know how to judge local insurers, understand the fine print, and ask the right questions before you switch carriers or renew your current policy.
The 2026 Auto Insurance Landscape in Indiana
Before you can effectively compare quotes, it helps to understand the broader market. Over the past few years, the auto insurance industry has experienced significant shifts. Supply chain disruptions, inflation, and the rising cost of parts have forced carriers to adjust their rates nationwide.
Indiana has traditionally enjoyed more affordable insurance premiums compared to the national average. However, urban centers like Indianapolis come with higher risks than rural areas, meaning residents in Marion County and surrounding suburbs often see higher premiums than drivers in other parts of the state. According to recent 2026 data from Experian, the average cost of full coverage car insurance in Indiana is around $1,695 annually. Yet, depending on your ZIP code, driving history, and vehicle type, your specific rates in Indianapolis could easily trend higher.
Part of this cost increase is driven by the vehicles we drive. Today, a minor bumper replacement might involve recalibrating backup cameras, radar sensors, and lane-departure systems. What used to be a simple $500 repair can now easily exceed $3,000. Additionally, the Indiana Criminal Justice Institute continuously monitors crash data, and while the state has made excellent progress in reducing overall roadway fatalities in recent years, the frequency of urban traffic collisions keeps local claims high.
All of these factors mean that finding reliable local car insurance in Indianapolis is more important than ever. You need a policy that keeps up with the actual cost of modern risks. For a deeper dive into the state rules, you can review our Indiana Car Insurance Guide.
Dissecting Car Insurance Quotes in Indianapolis
When you request car insurance quotes in Indianapolis, IN, the numbers you receive are based on a complex algorithm. Insurers evaluate your age, driving record, credit history, marital status, and even the specific neighborhood where you park your car at night.
But the biggest variable you control is the coverage itself. Many drivers make the mistake of comparing two quotes side by side without realizing they are looking at completely different levels of protection. Here is a breakdown of what you should be evaluating when you review a quote.
Bodily Injury Liability
This covers the medical expenses of other people if you are at fault in an accident. Indiana law requires a minimum of $25,000 per person and $50,000 per accident. In 2026, a $25,000 limit is dangerously low. A single trip to the emergency room, an ambulance ride, and minor physical therapy can easily exhaust that amount. If the injuries exceed your coverage limits, you can be sued personally for the difference. We almost always recommend increasing these limits to protect your assets.
Property Damage Liability
This pays for the damage you cause to another person's vehicle or property. The Indiana state minimum is just $25,000 per accident. Think about the cars driving next to you on I-465. If you rear-end a brand new SUV or a luxury sedan, $25,000 will not cover the replacement or extensive repairs. When evaluating auto insurance companies in Indianapolis, ask them to quote you at $100,000 for property damage to see the price difference. It is usually only a few dollars more per month for significantly better protection.
Uninsured and Underinsured Motorist Coverage
Despite state laws, a surprising number of people drive without active insurance. Uninsured motorist coverage protects you and your passengers if you are hit by someone who has no insurance or by a hit-and-run driver. Underinsured motorist coverage kicks in if the at-fault driver has insurance, but their limits are too low to cover your medical bills. This is a critical component to verify when comparing car insurance companies in Indianapolis.
Comprehensive and Collision Coverage
Often referred to together as "full coverage," these two distinct options protect your actual vehicle. Collision covers damage from an accident with another vehicle or object. Comprehensive covers events outside your control, such as theft, vandalism, falling tree branches, or hitting a deer on a dark county road. Pay close attention to the deductibles on your quotes. A policy with a $2,500 deductible will have a much lower monthly premium than one with a $500 deductible, but you must be prepared to pay that higher amount out of pocket if you file a claim.
How to Judge Car Insurance Companies in Indianapolis
The cheapest premium is not always the best choice. Some auto insurance companies in Indianapolis are aggressive with introductory pricing to win your business, only to hike your rates significantly at your first renewal. Furthermore, a cheap policy is worthless if the claims process is a nightmare.
Here are the key factors you should use to judge and compare companies before making a commitment.
Claims Handling and Reputation
When you are standing on the side of the road in the freezing rain after an accident, you do not want to be put on hold by an out-of-state call center. You want responsiveness and empathy. Local Indianapolis car insurance companies, or local agencies that represent major national carriers, provide a distinct advantage. An independent agency like ours can step in to advocate for you during the claims process. Look at online reviews, ask friends for recommendations, and research how the company handles claim disputes.
Flexibility and Policy Customization
Your life is not static, and your insurance should not be either. The right company will offer flexible solutions that grow with you. Perhaps you are adding a newly licensed teen driver to your policy, or maybe you recently started driving for a rideshare company. You need a carrier that offers specific endorsements to cover these changes. If a company only offers cookie-cutter policies with no room for customization, they might not be the best fit for your long-term needs.
Financial Stability
An insurance policy is essentially a promise to pay. If a major weather event like a massive hail storm sweeps through central Indiana, thousands of claims will be filed simultaneously. You need an insurer with the financial backing to pay those claims promptly without risking insolvency. Independent rating agencies like AM Best provide letter grades for insurance carriers based on their financial strength. We always ensure our clients are placed with highly rated carriers.
For more insights into picking the right partner, you might find value in our guide on Choosing an Insurance Agency in Illinois and Indiana.
Insider Questions to Ask Before You Switch
Most consumers only ask one question when they shop for insurance: "How much does it cost?" To truly protect yourself, you need to dig deeper. Whether you are speaking with a captive agent, an independent broker, or a customer service representative online, you should ask these specific questions before signing on the dotted line.
Do you use OEM or aftermarket parts for repairs?
If your car is damaged, you want it repaired properly. Original Equipment Manufacturer (OEM) parts are made by the company that built your car. Aftermarket parts are made by third parties and may not fit or perform exactly like the original. Some carriers mandate the use of cheaper aftermarket parts to keep their costs down. If this matters to you, ask if the policy includes an OEM endorsement.
Does this quote include rental car reimbursement?
If your car is in the shop for three weeks following an accident, how will you get to work? Rental car reimbursement is an optional coverage that pays for a rental vehicle while yours is being repaired during a covered claim. When comparing car insurance companies in Indianapolis, IN, verify if this coverage is included and what the daily limit is. A $30 per day limit might not be enough to rent a vehicle comparable to your own.
What happens if my vehicle is totaled and I owe more than it is worth?
Vehicles depreciate rapidly. If you financed your car with a small down payment, you might owe the bank $25,000 on a car that is only worth $20,000 in actual cash value. If the car is totaled, standard insurance will only pay the $20,000, leaving you on the hook for the remaining $5,000. Gap insurance covers this difference. Ask if this coverage is available to add to your auto policy.
Are there hidden penalties for minor incidents?
Some carriers offer accident forgiveness programs, meaning your rates will not increase after your first at-fault accident. Other carriers will penalize you heavily for even a minor fender bender or a single speeding ticket. It is important to understand the company's internal rules regarding surcharges and driving record penalties.
For drivers with unique situations, such as needing an SR-22 or insuring a classic vehicle, asking these tailored questions is even more critical. You can learn more about these specific scenarios in our breakdown of Indianapolis Auto Insurance for SR-22, ZIP Code, and Collector Car Questions.
Why "Cheap" Isn't Always the Goal
We understand the appeal of saving money. Many drivers begin their search specifically looking for cheap auto insurance in Indianapolis, Indiana. With the rising cost of living, trimming a few dollars off your monthly budget sounds great in theory.
However, cheap insurance often comes with hidden trade-offs. The most common way a carrier artificially lowers your premium is by stripping away coverage. They might quote you the absolute state minimums, remove uninsured motorist coverage, increase your deductibles to $2,500, and remove essential add-ons like towing and rental reimbursement.
The money you save on a "cheap" policy over the course of a year can be wiped out in a single afternoon if you get into an accident and realize you do not have adequate protection. At The Haley Agency, our goal is not to find you the cheapest policy, but the most cost-effective policy that actually protects your family's financial future.
Maximizing Value Through Discounts
Instead of cutting coverage to save money, focus on maximizing your discounts. Insurance companies offer numerous ways to lower your premium without sacrificing protection.
- Bundling Policies: One of the most effective ways to save is to combine your auto insurance with your home or renters insurance under the same carrier.
- Telematics Programs: Many carriers now offer apps or plug-in devices that monitor your driving habits. If you drive safely, brake smoothly, and avoid late-night driving, you can earn substantial discounts.
- Good Student Discounts: If you have a high school or college student on your policy who maintains a B average or higher, you can often secure a lower rate.
- Safety Features: Ensure your carrier knows about every safety feature on your car, from anti-theft devices to advanced braking systems. If you are a business owner utilizing vehicles for work, personal auto insurance will not cover you properly. You will need a commercial policy. We cover the distinctions and growth trends in our article on Indiana Commercial Auto Requirements and Business Insurance Growth. Furthermore, managing your overall risk portfolio means looking beyond just your cars. Protecting your family with proper coverage is a holistic process, which you can read more about in our guide to Life Insurance Planning in Indianapolis for Families and Business Owners.
Taking the Next Step in Your Insurance Journey
Your auto insurance policy is your financial shield on the road. Navigating the busy streets of Indianapolis comes with inherent risks, but the right coverage gives you the confidence to drive with peace of mind.
When you sit down to review your coverage, do not just glance at the premium. Read the declarations page carefully. Understand your liability limits, know your deductibles, and verify that your uninsured motorist coverage is intact. Do not be afraid to ask hard questions of your agent or carrier. A good insurance professional will welcome those questions because it shows you are engaged in protecting your assets.
At The Haley Agency, we pride ourselves on education and transparency. We believe that an informed client makes the best decisions. We do the heavy lifting of shopping multiple reputable carriers to find the perfect intersection of value and comprehensive protection for your specific needs.
Ready to protect what you’ve built with coverage that actually fits? Contact The Haley Agency today to schedule a personalized policy review for your home, auto, life, or business insurance across Illinois and Indiana. You can get started by requesting a quote directly on our homepage. Let us help you find the right balance of protection and value for the road ahead.
By Joshua Haley & Team